Public liability insurance policies for labour hire firms can feel complex to compare when each option has different definitions, limits, exclusions and conditions. At Business Insurance Specialists (BIS), we evaluate these technical wording details alongside your host employer agreements, candidate screening procedures, and placement settings.
Key Takeaways
- Public liability cover addresses third-party injury and property damage arising from your business activities.
- Your employment, supervision and contract arrangements can affect your exposure.
- Clear information about worker duties, client sites and subcontractors helps us assess your needs.
- Our Labour Hire Insurance guidance can help you consider broader workforce risks.
Hi, I’m Tom Knox, Managing Director & Founder of Business Insurance Specialists. With experience in underwriting and commercial broking, I help staffing businesses make sense of public liability exposures.
When Can Public Liability Insurance for Labour Hire Respond?
When you place workers across offices, healthcare settings, construction sites or manufacturing plants, an incident can involve more than one business. Public liability insurance for labour hire may respond to claims alleging that your on-hire workers or business operations caused third-party injury or property damage, depending on the policy and circumstances.
The distinction between labour hire and direct placement matters. In a typical labour hire arrangement, your agency keeps the employment relationship and manages payroll, while the host employer directs the worker’s day-to-day tasks on site. With a direct placement, the client engages the worker on its own payroll.
Because labour hire providers retain an ongoing connection with on-hire workers, a third party may bring a claim against the agency, the host employer or both. Requirements vary by industry, licence and contract, so it helps to review how your placement arrangements may affect your exposure.
What Other Covers and Subcontractor Arrangements Should You Consider?
Looking at your wider insurance arrangements can help you understand the risks around a labour hire operation. We commonly discuss the following commercial liability covers with staffing businesses:
- Public and Product Liability: covers injury or damage to third parties arising from your business activities.
- Professional Indemnity: covers financial loss suffered by third parties due to negligent advice, an error or an omission in recruitment or candidate screening services.
- Management Liability: protects business owners and managers against liabilities arising from how the business is run.
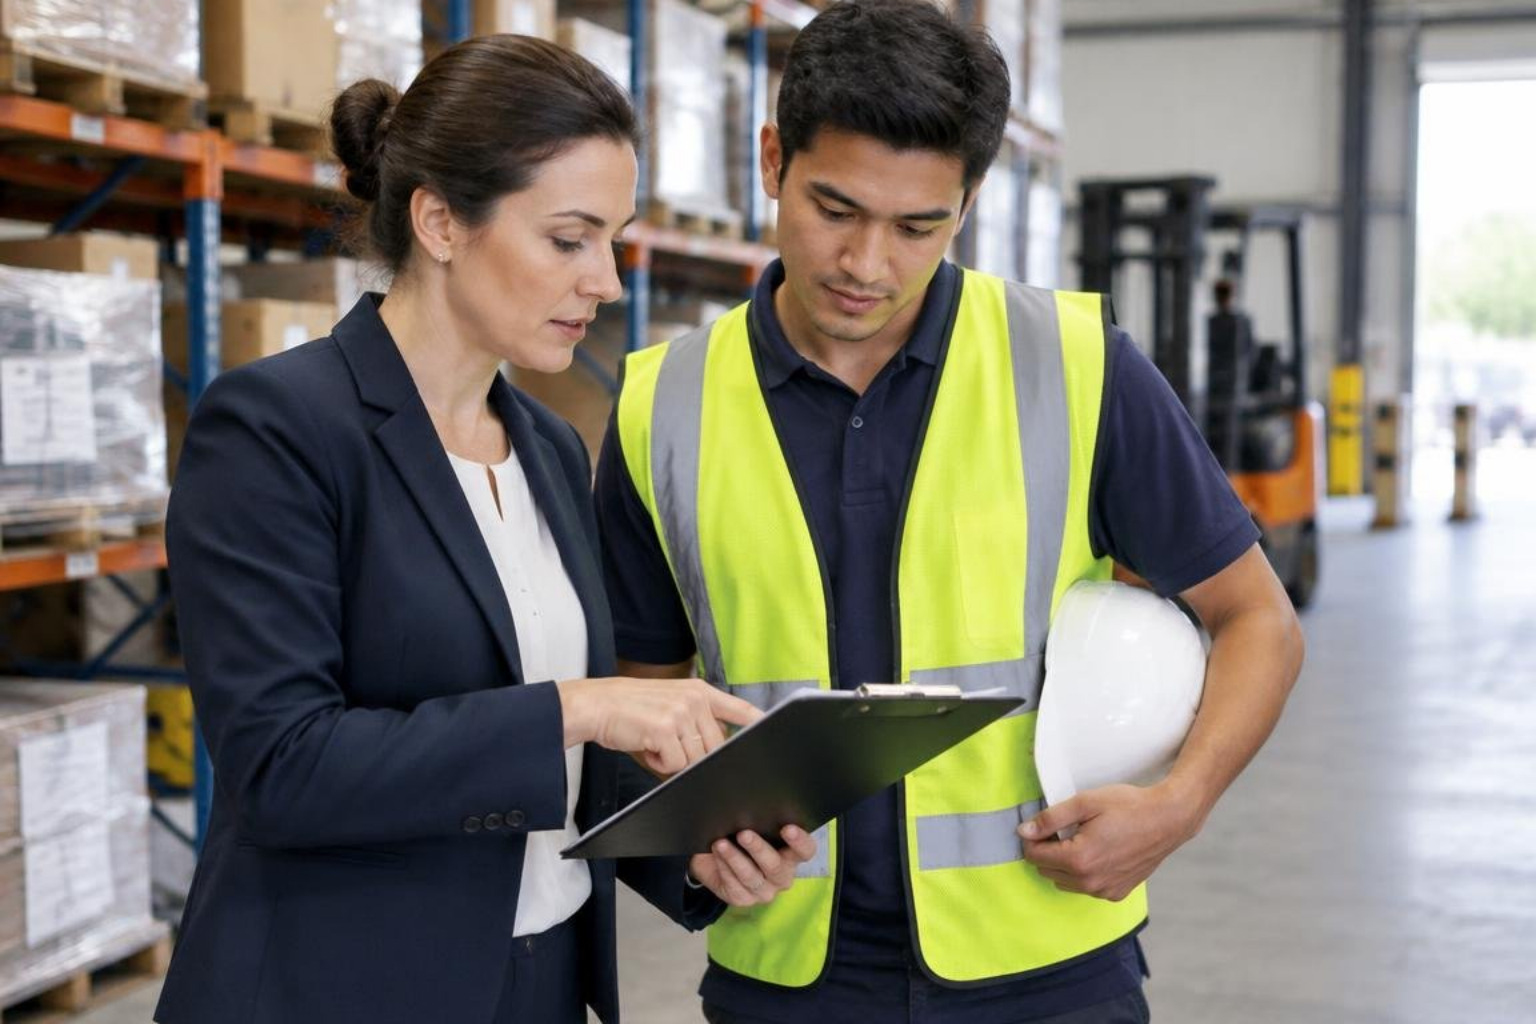
Staffing businesses often engage both employees and independent subcontractors. When we arrange cover, it is essential to describe how external personnel work. Insurers may assess labour-only subcontractors differently from independent, bona fide subcontractors.
| Subcontractor Type | Typical Operational Characteristics | Insurance Consideration |
|---|---|---|
| Labour-only subcontractors | Work under host or agency direction, use provided tools and are paid for their time | Insurers may assess them similarly to direct employees for liability purposes |
| Bona fide subcontractors | Work independently, supply specialist equipment and quote for complete jobs | They may be expected to hold and maintain their own valid liability policies |
How and when a policy responds depends on its wording and the circumstances of a loss. We can help you consider how your workforce arrangements fit with your broader insurance programme.
How Public Liability Insurance for Labour Hire May Respond to Site Incidents
On-hire workers operate in busy environments where accidents can happen. For example, a worker using materials-handling equipment may damage warehouse racking and third-party stock. In another situation, equipment left unsecured in a public area may lead to a third-party trip and injury.
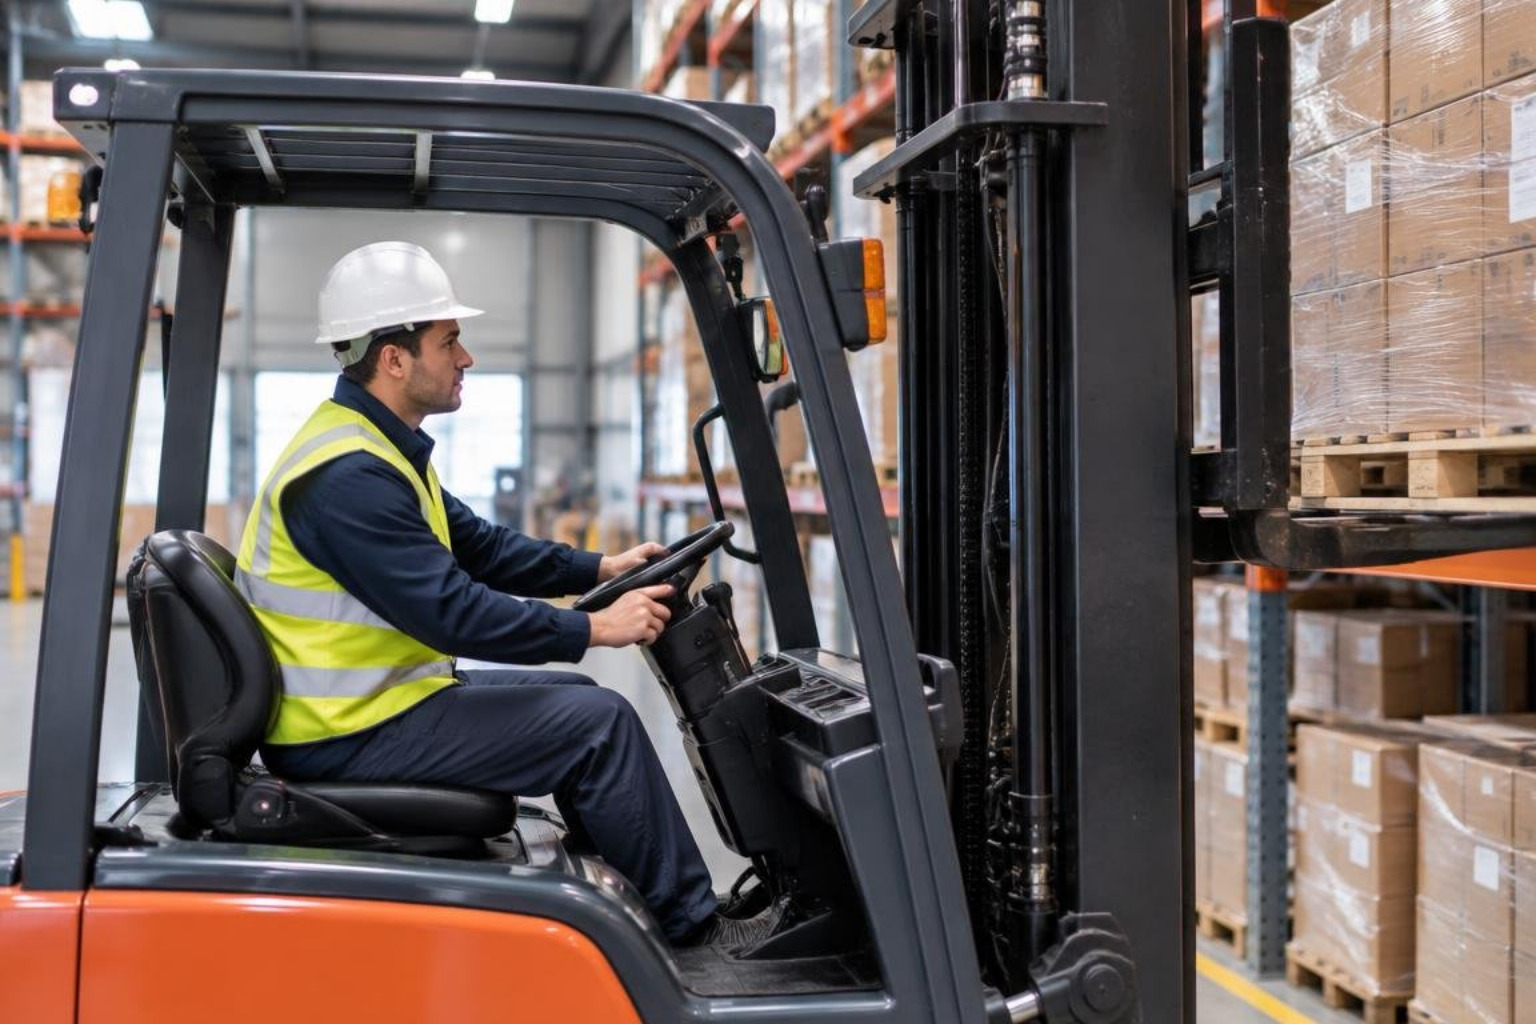
In these situations, a claim may be brought against the labour hire agency, the host employer or both. Whether an insurer accepts indemnity depends on the policy terms, applicable endorsements, site supervision and contractual risk allocation. If you are reviewing your arrangements, you can request a discussion through our Insurance Quotes page.
How We Help You Assess Labour Hire Exposures
We work with you to understand your contracts, placement activities and worker supervision arrangements, then explain the relevant policy terms in plain English. If you are moving into higher-risk industries, engaging new subcontractors or reviewing a host employer agreement, gather your current policies and document any operational changes before getting in touch.
Talk to Us About Your Labour Hire Liability Risks
Managing labour hire liability risks starts with a clear picture of your contracts, placement activities and worker supervision arrangements. Business Insurance Specialists (BIS) is a Brisbane-based commercial insurance brokerage that works on your behalf, explaining policy terms in plain English and helping identify potential gaps across your workforce operations.
If you are expanding into higher-risk industries, engaging subcontractors or reviewing a host employer agreement, we can help you prepare. Start with an Uninsured Risk Review, request a discussion through Insurance Quotes, or Contact Us. At claim time, BIS assists with lodging and managing claims through to finalisation, while the insurer determines claim decisions. If an underwriter questions or disputes a claim, Business Insurance Specialists steps in as your independent advocate, analyzing host contract indemnities, reviewing site supervision logs, and submitting formal counter-arguments through the insurer’s Internal Dispute Resolution (IDR) process.
The information in this article is general in nature and does not take into account your objectives, financial situation or needs. Before making a decision about insurance, consider whether the information is appropriate for you and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD).
Frequently Asked Questions About Public Liability Insurance for Labour Hire
What does public liability insurance for labour hire cover?
Public liability insurance for labour hire covers injury or damage to third parties arising from your business activities, along with associated legal defence costs for a covered claim. How and when a policy responds depends on its wording, declared business activities, endorsements and the circumstances of the incident, so staffing businesses should read the Product Disclosure Statement (PDS).
How does labour hire differ from temporary placement for insurance?
Labour hire involves an agency providing workers to a host employer while maintaining the underlying employment relationship and payroll responsibilities, whereas temporary direct placement introduces a worker who is engaged directly by the client. These differing operational models alter the degree of control and exposure held by the agency, and the insurer’s assessment of risk will depend on the exact contractual terms in place.
What happens if sub-contractors are incorrectly classified?
Incorrectly classifying sub-contractors or misrepresenting how workers are supervised on site may impact how an insurer assesses a claim at the time of loss. The outcome of any claim depends entirely on the specific policy conditions, accurate risk declarations, and individual circumstances, making open communication with your broker essential during policy placement.
What other insurance policies should labour hire businesses consider?
In addition to public liability, labour hire providers often consider professional indemnity cover to address financial losses resulting from recruitment errors, as well as management liability cover to protect company directors and officers. Queensland workers’ compensation is provided exclusively by WorkCover Queensland, and businesses should seek advice from a qualified solicitor for legal matters or an accountant for tax inquiries.
How are labour hire insurance premiums determined?
No fixed price exists for labour hire coverage, as premiums depend on the specific business, chosen coverage limits, and overall risk profile. Underwriters evaluate factors such as annual turnover, wages, candidate screening processes, the specific industries into which personnel are placed, and past claims history to determine the applicable premium.
