A management liability package brings together insurance covers for business decisions, employment practices, and governance, but policies can feel hard to compare when each has different definitions, limits, exclusions and conditions. Business Insurance Specialists (BIS) helps company directors and managers look past the headline terms to evaluate options in plain English.
Key Takeaways
- Management liability covers claims arising from decisions made by owners, directors and managers.
- A package can combine several covers, including directors and officers liability, statutory liability and employment practices liability.
- Good governance helps manage risk, but insurance provides financial protection when claims arise.
- Review limits, exclusions and claims conditions before choosing cover. Our Small Business Insurance Solutions page is a starting point for considering your broader insurance needs.
Hi, I’m Tom Knox, Managing Director & Founder of Business Insurance Specialists. My background in underwriting and commercial broking since 1993 helps me explain where a management liability package may fit within a business’s insurance program.
Comprehensive Protection with a Management Liability Package
Running a company involves navigating legal duties, commercial decisions and regulatory frameworks. The Australian Securities and Investments Commission provides guidance on ASIC Director and Officer Responsibilities under corporate law, highlighting the expectations placed on company leadership. A management liability package is designed to assist company directors, officers and the business entity itself against liabilities arising from managerial actions and governance responsibilities.

Every policy is structured differently. Cover for public relations crisis management, civil liabilities and other insured responses depends entirely on the terms, conditions and exclusions contained in the Product Disclosure Statement (PDS). Furthermore, certain statutory fines and penalties cannot be insured under Australian law. Reviewing contractual obligations alongside your broker through a service such as an insurance contract review can assist leadership in identifying potential exposures.
| Policy Feature | Management Liability Package | Professional Indemnity Insurance |
|---|---|---|
| Primary Scope | Protects leadership and the company against liabilities arising from internal management decisions, corporate governance and employment practices. | Protects businesses against financial loss suffered by third parties arising from negligent advice, design, error or omission in professional services. |
| Typical Target | Directors, officers, managers and the corporate entity. | The business entity and its practitioners delivering fee-for-service advice. |
| Key Risk Triggers | Employment disputes, regulatory investigations, fiduciary breaches, internal crime. | Breaches of professional duty, incorrect advice, documentation errors. |
| Policy Limitations | Does not cover everyday trading losses or uninsurable statutory fines; terms depend on policy wording. | Does not cover internal director mismanagement or standard contractual debt; terms depend on policy wording. |
Many enterprises choose to integrate management liability alongside their broader business insurance package. As a Brisbane-based insurance brokerage, BIS acts as a client advocate to help business owners understand the nuances of these commercial covers.
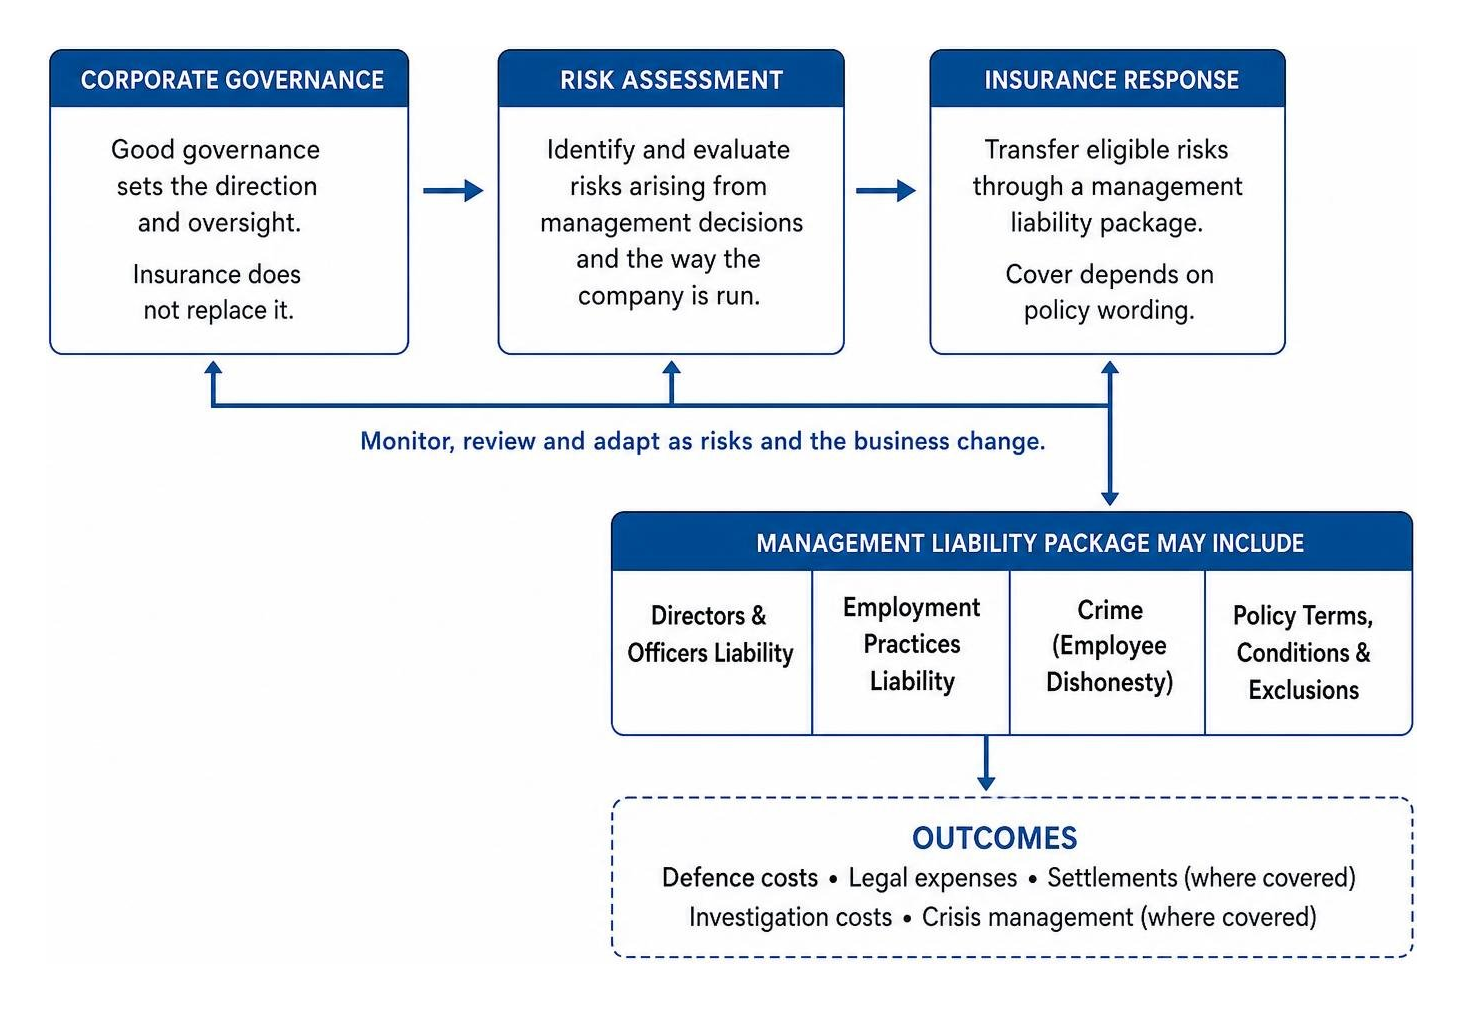
Core Coverages within a Management Liability Package
While individual policies vary, a comprehensive package generally brings together several core sections under a single combined arrangement:
- Directors and Officers (D&O) Liability: Responds to claims alleging wrongful acts, breaches of duty or neglect by individual leaders in their managerial capacity, with the policy response depending on the wording.
- Corporate Entity Defence: Extends certain policy responses to the company itself when the entity is named in particular legal actions or regulatory investigations.
- Employment Practices Liability (EPL): Addresses allegations brought by current, former or prospective employees relating to unfair dismissal, harassment, discrimination or breach of employment terms.
- Statutory Liability: May respond, where lawful and subject to policy wording, to matters arising from unintentional breaches of specific statutory legislation, such as workplace health and safety laws.
- Commercial Crime and Fidelity: Protects against direct financial loss from dishonest acts. Cover for Social Engineering and Funds Transfer Fraud overlaps between Management Liability and standalone Cyber policies, with some management liability packages offering lower sub-limits without requiring strict dual-authorisation controls.
- Tax Audit Support: May provide a policy response when the business is responding to an official audit or investigation by the Australian Taxation Office (ATO).

When an incident occurs, following proper notification procedures is essential. We assist businesses during the commercial insurance claims process, helping policyholders liaise with underwriters from the initial notification through to final resolution.
What Does a Management Liability Package Cover for Leadership Teams?
Determining whether your organisation requires management liability protection involves evaluating several operational risk factors. Private companies, family businesses and unlisted entities face many of the same governance exposures as larger corporations:
- Workforce Size and HR Complexity: As staff numbers increase, the potential for employment disputes or tribunal proceedings can grow.
- Regulatory Oversight: Businesses operating in regulated environments face regular scrutiny regarding safety, fair trading and industry standards.
- Shareholder and Board Dynamics: Companies with non-executive directors, minority shareholders or external investors experience distinct fiduciary exposures.
- Financial and Transactional Operations: Direct exposure to supply chains, customer funds and electronic payment systems can elevate crime and governance risks.
A management liability package is not a single product with a fixed scope. The policy response depends on the wording, the nature of the allegation and the role of the person involved. For example, a directors and officers section may respond to claims alleging a breach of duty, while an employment practices section may address allegations such as unfair dismissal or discrimination. Statutory liability cover may respond, where lawful and subject to policy wording, to matters arising from unintentional breaches of specific legislation such as workplace health and safety laws.
When reviewing your exposures, we look at how your governance framework, employment arrangements and contractual obligations interact. This helps us identify where a management liability package may respond and where other covers, such as a business insurance package, may be more appropriate. To explore tailored solutions, you can request commercial insurance quotes or contact our Brisbane team directly to review your risk profile.
Working with BIS to Review Management Liability Risks and Policy Wording
Managing commercial risk requires an ongoing assessment of corporate governance practices, operational controls and insurance coverage. A management liability package serves as an important safeguard for decision-makers, provided the limits, excesses and sub-limits align with the organisation’s genuine exposure.
When you work with BIS, we start by reviewing your current governance arrangements, employment practices and contractual obligations. This helps us identify where a management liability package may respond and where other covers, such as a business insurance package, may be more appropriate. We can also review your existing insurance policies to check for gaps or overlapping terms.
If you are preparing for a renewal or considering cover for the first time, gathering your company constitution, shareholder agreements, employment contracts and any recent regulatory correspondence is a practical first step. Our team can then discuss how different policy wordings treat matters such as defence costs, investigation responses and claims notification. You can request commercial insurance quotes or contact Business Insurance Specialists during business hours to speak with our Brisbane-based team.
Business Insurance Specialists is an established Brisbane-based insurance brokerage dedicated to acting as an advocate for clients across Queensland and Australia. Our experienced team provides clear, practical advice to help you evaluate policy terms, structure appropriate protection and navigate the claims process. For personalised support regarding your governance and liability policies, you can request commercial insurance quotes or contact Business Insurance Specialists during business hours. Our Small Business Insurance Solutions page is also available if you are reviewing your broader insurance needs.
The information in this article is general in nature and does not take into account your objectives, financial situation or needs. Before making a decision about insurance, consider whether the information is appropriate for you and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD).
Frequently Asked Questions About Management Liability Packages
Who Needs a Management Liability Package for Private Company Protection?
Private companies, proprietary limited businesses, unlisted entities, corporate trustees and non-profit organisations often consider this cover. Directors and senior executives carry legal responsibilities under corporate law, meaning personal assets and company balance sheets can be affected if allegations of wrongful management decisions arise. Whether a policy responds depends on individual circumstances and policy wording.
How Does Management Liability Differ from Professional Indemnity?
Management liability addresses claims arising from internal business governance, leadership decisions, employment disputes and statutory compliance. In contrast, professional indemnity insurance covers civil liability for financial loss suffered by third parties due to negligent advice, design, errors or omissions in professional services provided to clients.
Does a Policy Cover WorkCover Queensland Compensation Claims?
Employer workers compensation in Queensland is administered by WorkCover Queensland, and a management liability policy does not replace statutory workers compensation for injured workers. Management liability policies may, however, provide a policy response in official investigations following a workplace safety incident, subject to policy terms and legal restrictions on insuring statutory penalties.
Can Management Liability Cover Insolvent Trading Claims?
Coverage for insolvent trading allegations varies significantly across insurers and is subject to strict policy exclusions, conditions and legislation. If your business is facing solvency concerns or potential trading actions, direct all legal questions to a qualified solicitor.
How Do Leadership Teams Lodge a Claim under This Cover?
Policyholders must notify their insurance broker or insurer as soon as they become aware of a claim, investigation or circumstance that could give rise to a claim. Most policies require written insurer consent before appointing advisers or resolving matters. The insurer determines claim decisions based on policy terms and circumstances. If an underwriter questions or disputes a claim, Business Insurance Specialists works on your behalf to review the policy wording, examine the details of the matter, and present technical arguments directly to the underwriter through the insurer’s internal complaints and Internal Dispute Resolution (IDR) process.
