Vital Checks When Arranging Used Plant Insurance in Australia
Used plant insurance may help protect the second-hand machinery your civil business relies on when theft, accidental damage or another insured event disrupts a job. The right conversation starts with how you use each machine, whether you own or hire it, and how a loss could affect your work.
Key Takeaways
- Plant and Equipment Insurance may be arranged for owned machinery, hired-in plant, or both, depending on the policy.
- The insured value should reflect the machinery and your operating circumstances.
- Policy wording can treat accidental damage and mechanical breakdown differently.
- Hire agreements, transport arrangements and site security can affect the insurance considerations.
Hi, I’m Tom Knox, Managing Director & Founder of Business Insurance Specialists. I draw on my experience in underwriting and commercial broking to help civil operators have practical conversations about insurance for second-hand machinery.
What Does Used Plant Insurance Help Civil Operators Manage?
Used plant insurance may help your business manage the financial impact of insured events involving second-hand excavators, loaders, rollers and graders. It can be relevant when a machine is stolen, damaged in an accident, affected by fire or storm, or involved in a rollover, depending on the policy wording and your circumstances.
For many civil operators, second-hand equipment is a practical way to grow a fleet. The key is making sure the insurance conversation reflects the machinery you actually use, where it travels and whether it is owned, financed or hired. BIS can help you work through those details in plain English.
It is also worth checking the wider risks around a job. Machinery can be stored at a depot, moved between Queensland worksites or used near public roads. Contract requirements and your existing policy may affect the cover you need to discuss, so it is better to review the wording before a problem arises.
Damage to underground services or another person’s property raises different considerations from damage to your own machinery. We can help you compare those risks with your current arrangements and discuss the relevant policy wording. If you are reviewing your options before renewal or a new project, you can Request an Insurance Quote from our team.
How Should You Value and Insure Second-Hand Machinery?
When you are reviewing used plant insurance, start with the machinery list. The insured value should reflect the equipment you have, how it is used and the basis set out in the policy. Keeping purchase documents, service records and recent valuations handy gives us a clearer picture when we discuss your cover.
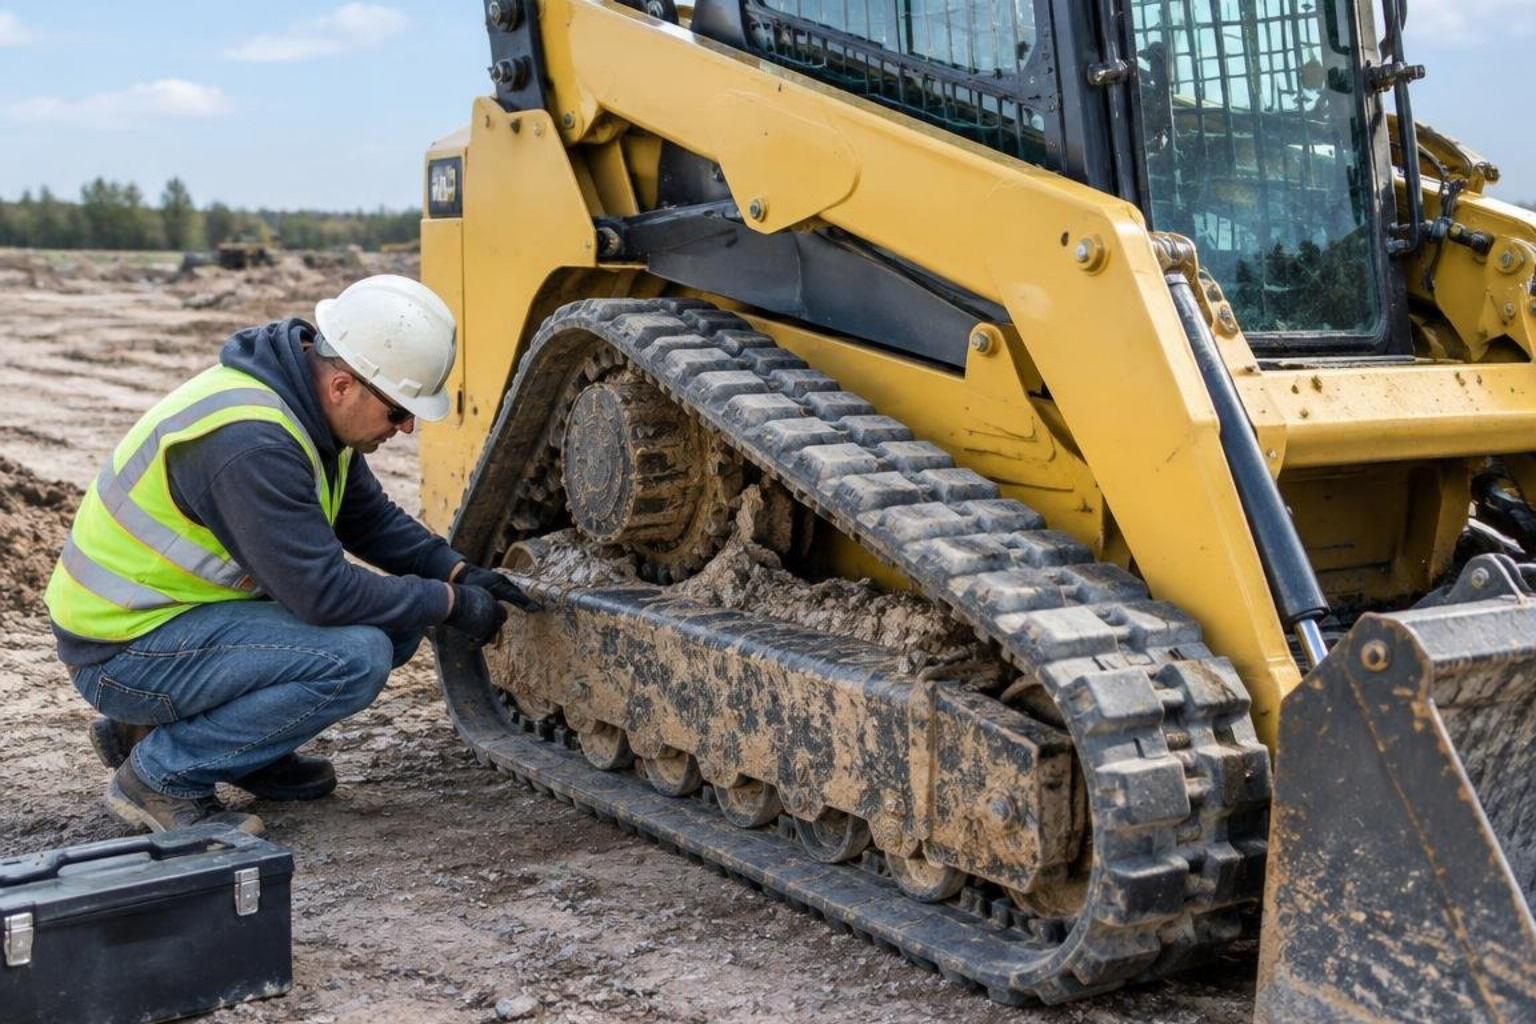
Owned machinery and hired-in plant can create different questions. With owned plant, you may want to discuss the value of the machine, transport between sites and the effect of downtime. With hired-in plant, the hire agreement may set out responsibilities for damage, theft, security or continuing hire charges. The policy, insurer and circumstances determine how cover may respond.
If you are dry hiring equipment, read the agreement before signing and ask us to review the insurance considerations with you. Requirements can vary by industry, licence and contract, and legal questions about the agreement should go to a solicitor.
Accidental Damage and Mechanical Breakdown
Accidental damage and mechanical or electrical breakdown are not always treated the same way. Used plant policies may respond to events such as collision, fire, rollover or storm, while wear and tear or a mechanical failure may be excluded or require separate consideration. The Product Disclosure Statement (PDS) explains the policy terms, exclusions and limits.
Service history can be useful when reviewing older machinery. Keep maintenance logs, oil sampling reports and service records organised so you can show how the equipment has been looked after. If an incident occurs, BIS can assist with lodging and managing a claim through to finalisation, while the insurer determines claim decisions.
Managing Day-to-Day Risks Around Your Civil Machinery
Insurance is only one part of managing second-hand machinery. The way you maintain equipment, secure it and document its use can help you reduce disruption when something goes wrong and make it easier to explain the circumstances of a loss.
Keep logbooks, service invoices and oil sampling reports in one place. These records can help show how a machine has been operated and maintained in line with the manufacturer’s recommendations. They can also support a conversation about the machinery values listed on your policy, although valuation and claim outcomes depend on the policy and circumstances.
For plant left in compounds, remote worksites or while moving between projects, consider practical security measures such as locked gates, immobilisers, Global Positioning System (GPS) tracking and documented check-in procedures. No measure prevents every incident, but a consistent approach can reduce risk and help answer questions from an insurer after a loss.
If you hire machinery, the agreement may set expectations around security, operator competence and incident reporting. We can help you look at the insurance considerations before the equipment arrives on site and identify where your operational practices and cover may need closer attention. Legal questions about contractual obligations should go to a solicitor.
Let us know when you acquire or dispose of machinery, change worksites or take on new types of work. Keeping your machinery list current gives us a better starting point when we review your cover.
Next Steps for Protecting Your Used Civil Plant
As your civil operation grows, it helps to review your machinery list before renewal, before signing a hire agreement and whenever the way you use your equipment changes. Bring together your current policy, machinery details, maintenance records and hire agreements so we can have a practical conversation about the risks that matter to your business.
Business Insurance Specialists (BIS) works on your behalf when dealing with insurers and explains cover in plain English. We can help you review machinery values, hired-in plant considerations and the policy wording that applies to your work. To start the conversation, Contact BIS or Request an Insurance Quote. You can also explore our Plant and Equipment Insurance service for a broader overview.
The information in this article is general in nature and does not take into account your objectives, financial situation or needs. Before making a decision about insurance, consider whether the information is appropriate for you and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD).
Frequently Asked Questions About Used Plant Insurance
What is used plant insurance for?
Used plant insurance may help protect second-hand machinery against insured events such as theft and accidental damage. The available cover, limits and exclusions depend on the policy wording, insurer and your circumstances.
Can used plant insurance include owned and hired machinery?
It may be possible to discuss cover for both owned machinery and hired-in plant. Whether either is included, and on what terms, depends on the policy, insurer and the relevant hire arrangements.
How should I review my machinery’s insured value?
Keep your machinery list, purchase documents, maintenance records and any available valuations ready for review. The appropriate valuation basis depends on the policy wording and the circumstances of your equipment.
Is mechanical breakdown included in used plant insurance?
Mechanical breakdown is not automatically included with accidental damage cover. Availability, exclusions and any additional options depend on the insurer, the machinery and the policy terms.
What should I prepare before speaking with BIS?
Have your current policies, machinery list, service records and hire agreements available, and note any changes to where or how equipment is used. What we need to review will depend on your circumstances and the insurer’s requirements.
