Strata insurance policies can feel complex to compare when each option has different definitions, limits, exclusions and conditions. At Business Insurance Specialists (BIS), we help Brisbane body corporate committees look past headline terms to evaluate whether their common property, building replacement valuations, and storm exposures are properly covered.
Key Takeaways
- BIS works for your body corporate and can help you compare available policy options.
- Current building replacement valuations can help your committee consider the risk of underinsurance.
- An Uninsured Risk Review can help identify areas your committee may want to discuss.
- Insurance requirements vary, so it helps to review them alongside your scheme’s circumstances.
- We can support you with policy comparisons and claims advocacy, while the insurer makes final claim decisions.
Hi, I’m Tom Knox, Managing Director & Founder of Business Insurance Specialists. With experience across underwriting and commercial broking, I help Queensland body corporate committees make sense of strata insurance decisions and renewal risks.
Why Bodies Corporate Work with Strata Insurance Brokers
As a strata committee, you are making insurance decisions that affect common property and lot owners. We help you compare available options from insurers and understand what those options may mean for your scheme.
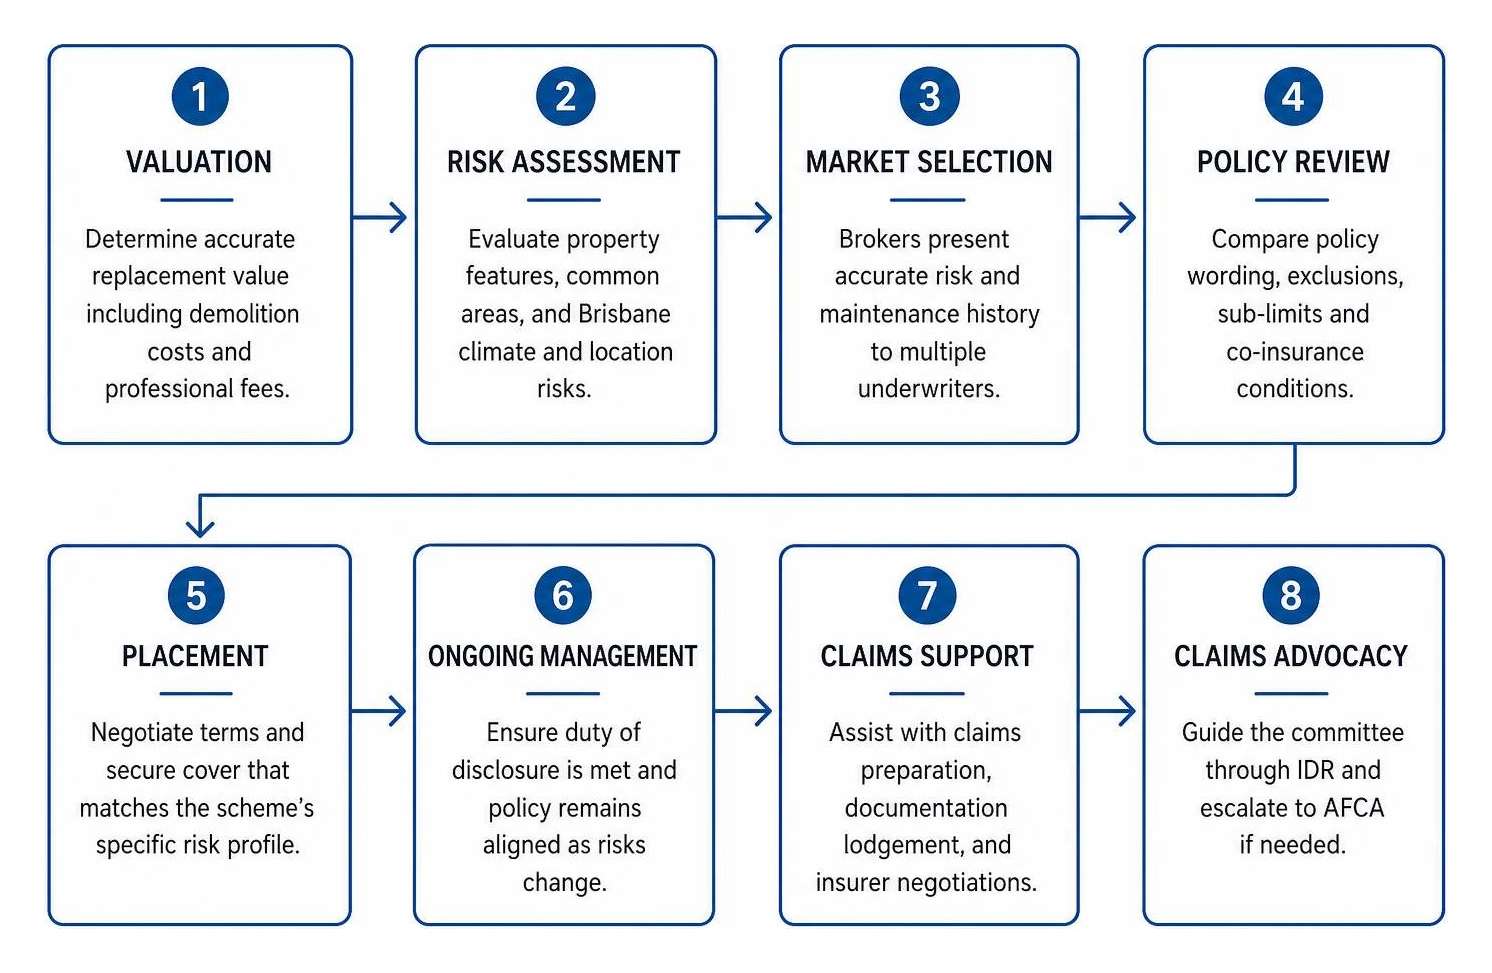
Policy wording can vary between insurers, and the detail matters. BIS can talk you through exclusions, which are things a policy may not cover, and sub-limits, which are lower limits for particular parts of cover. We also help you present accurate property information, security, construction, pro-active maintenance records, cover requirements and claims history when seeking available options.
If your scheme needs to make a claim, we assist with lodging, managing, and advocating on your behalf through to finalisation. If an underwriter questions or disputes a claim, Business Insurance Specialists acts for your body corporate, reviewing policy wording, examining building reports, and submitting technical counter-arguments through the insurer’s formal Internal Dispute Resolution (IDR) process.
How to Structure and Value Body Corporate Insurance
Reviewing building replacement costs helps your committee assess the amount to insure. Changes in construction material costs, specialist labour availability and building requirements can make older valuations outdated. An outdated insured amount may leave a funding gap after a loss. How and when a policy responds depends on its wording.
In Brisbane, it is sensible to consider severe weather risks such as hail, heavy rain and water entering buildings when you review cover. We can help your committee work through reports from quantity surveyors, who estimate construction costs, and consider demolition, professional fees and rebuilding when assessing the amount to insure.
| Review area | What we help you consider | Our role |
|---|---|---|
| Market access | Available insurer options | We help compare policy terms |
| Policy advice | What is and is not covered | We explain terms in plain English |
| Claims support | Support at claim time | We assist with lodging and managing claims; the insurer decides claims |
| Risk review | Property changes and risks worth discussing | We help review the information relevant to your scheme |
We can help your committee identify areas to discuss across shared lifts, swimming pools, basements and car parks. If unexpected damage occurs, our Make a Claim support can help with claim coordination, depending on the insurer and your circumstances. Property maintenance and building resilience are also useful considerations when insurers assess property risk.
When you are ready to review your scheme’s circumstances, we can talk through the available options with you.
Queensland Body Corporate Compliance and Premium Considerations
Insurance requirements can vary by depending upon your scheme’s circumstances. We can help you review the insurance information. For example, it is important to disclose if your building has any cladding, or known defects.
When reviewing cover, we can help your committee consider building replacement values and public liability limits, with terms depending on the policy and your circumstances. Public liability covers injury or damage to third parties arising from common property areas of your strata, subject to the policy wording. Depending on your scheme, we can also discuss committee members’ liability also known as office bearers’ liability, fidelity guarantee, which may protect scheme funds against dishonest acts, and machinery breakdown for shared equipment.
When we talk about premiums across Brisbane and South East Queensland, we usually look at factors such as:
- Storm and flood exposure, including proximity to waterways and low-lying land.
- Claims history, including past water damage or structural claims.
- Building condition and age, including roof integrity, plumbing and maintenance.
- Excesses, meaning the amount payable towards a claim depending on the policy.
- Insurance market conditions, including insurer capacity and reinsurance, which is insurance purchased by insurers.
For schemes with mixed commercial operations or light manufacturing on lower levels, we can help you be aware of potential issues in obtaining insurance with certain tenancy types. Prior to signing a new commercial lease with your tenant, please feel free to contact us as we are happy to advise of any implications or concerns relating to a tenancy change. Before renewal, gather your current policy, recent valuation and a record of changes to the building or its use so we can discuss the available options.
Preparing Your Body Corporate for Its Next Insurance Renewal
A little preparation before renewal can make the conversation much clearer. We encourage your committee to gather current replacement valuations, review maintenance records and note any changes to lots or common property before you start comparing available options.
We can review policy exclusions and excesses with you and present available insurance options. An Insurance Contract Review can help your committee understand how proposed wording applies to shared buildings, common areas and your scheme’s risks. Final terms and claim outcomes depend on the policy wording, the insurer’s assessment of the risk and the specific facts of an incident.
BIS delivers insurance broking with a focus on client advocacy, responsive service and clear explanations. We are here to help your committee review its insurance needs in a practical way.
To review your body corporate cover, request a Strata Insurance Quote or Contact Us to speak with our team.
The information in this article is general in nature and does not take into account your objectives, financial situation or needs. Before making a decision about insurance, consider whether the information is appropriate for you and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD).
Frequently Asked Questions About Strata Insurance in Queensland
When should a body corporate engage strata insurance brokers in Brisbane?
It helps to get in touch well ahead of your scheme’s annual renewal date or Annual General Meeting (AGM). That gives your committee time to gather building records, review replacement valuations and consider available policy options with lot owners. The time needed depends on the insurer and your scheme’s circumstances.
How can a body corporate check its insurance requirements in Queensland?
Requirements can vary by your scheme’s circumstances. We can help you review your current insurance and explain the available options, with cover depending on the policy wording and circumstances.
How do brokers assist with building valuations and underinsurance risk?
We can help your committee review reports from quantity surveyors, who estimate construction costs, and consider changes in replacement costs. The insured amount should be reviewed against current replacement costs, and how and when a policy responds depends on its wording. We can help you assess the amount to insure, while the final amount remains your committee’s decision.
How do we support a body corporate with a strata claim?
We can assist with lodging and managing a claim through to finalisation and communicate with the insurer on your behalf. How and when a policy responds depends on its wording and the circumstances. While we advocate for you during the assessment, the insurer makes the final decision on claim acceptance and settlement.
What factors influence strata insurance premiums across South East Queensland?
Strata premiums across Brisbane and Queensland can be influenced by severe weather exposure, the scheme’s claims history, property age, maintenance history and construction materials. Broader market conditions, including reinsurance, which is insurance purchased by insurers, can also affect premiums. Premiums and excess options depend on the insurer and your scheme’s circumstances.
