Business insurance policies can feel complex to compare when each option has different definitions, limits, exclusions and conditions. At Business Insurance Specialists (BIS), we work with you to evaluate these wording details against changing exposures and ensure your cover matches your operational priorities.
Key Takeaways
- A considered review can connect your insurance arrangements with business priorities and contingency plans.
- Looking at day-to-day controls and contractual commitments can reveal areas that need attention.
- An uninsured risk review helps distinguish exposures you retain from those that may be transferred to insurance.
- Regular conversations can keep coverage decisions relevant as your operations shift.
Hi, I’m Tom Knox, Managing Director & Founder of Business Insurance Specialists. My background across underwriting and commercial broking helps me guide Australian businesses through practical risk management and insurance decisions.
How Can Structured Risk Management Insurance Services Help?
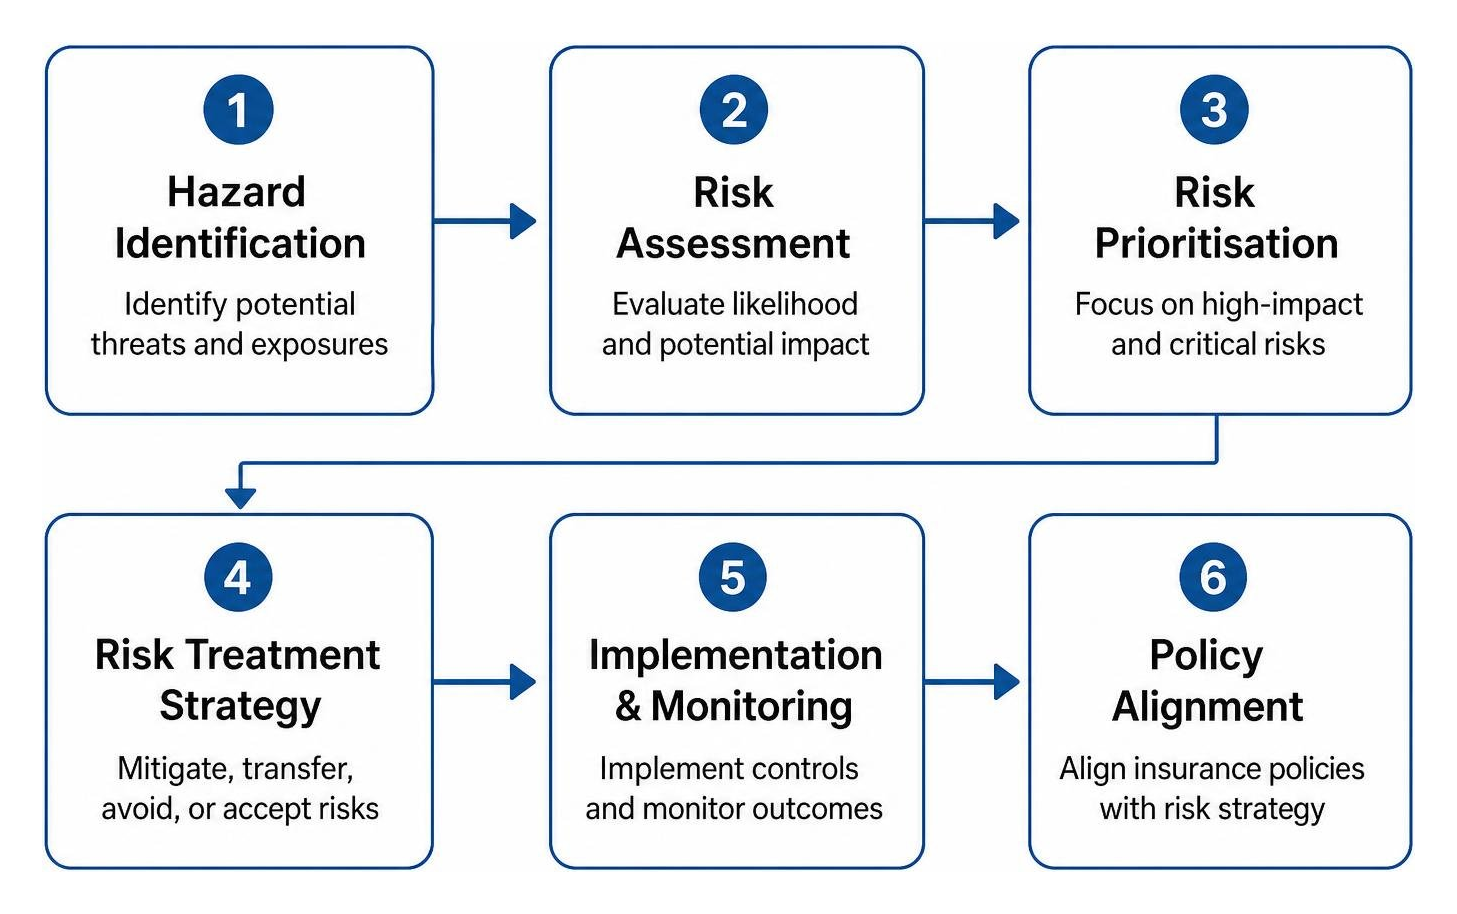
Risk management insurance services give you a clearer starting point for assessing exposures, operational controls and current policies. We use an uninsured risk review to separate retained exposures from risks that may be insured, helping you plan for interruptions and cash-flow pressure.
Risks That Can Change with Your Operations
New technology, changing work practices and reliance on digital systems can create exposures that were not part of your original arrangements. Queensland weather events can also affect premises, staff and supply chains, so it is worth considering how your business would respond.
Contracts with suppliers, landlords or head contractors can allocate responsibility for a loss in ways that affect your insurance needs. We can help you compare those obligations with your policy terms, while a solicitor can advise on the legal position. Insurance requirements differ across industries, licences and contracts.
Practical controls and sensible procedures can reduce the chance or impact of an incident. Insurance may then assist with a covered loss, subject to the policy wording.
Reviewing your premises can bring everyday hazards into focus and identify practical improvements to safety or security.
Aligning Commercial Insurance with Business Growth
As your team, assets or operations change, your insurance needs may change with them. We can help you review your existing arrangements so your cover remains relevant to the way your business operates.
Some businesses fund part of a loss themselves through deductibles or self-insured retentions. We can explain what those terms mean, discuss your financial position and help you consider your ability to manage claims and fund losses. How and when a policy responds depends on its wording.
Integrating Risk Management Insurance Services into Commercial Operations
We look at insurance alongside workplace safety, environmental responsibilities, emergency preparedness and business continuity planning. This gives you a clearer picture of how your business could keep operating after a disruption.
Public liability insurance generally covers injury or damage to third parties arising from business activities, depending on the policy. Insurance can complement practical plans for responding to incidents and keeping your business operating. To discuss your arrangements, you can request insurance quotes.
What a Structured Insurance Review Can Include
A structured review looks at your operations, assets, responsibilities and business plans alongside your insurance. We use that information to help you understand your options and the policy terms that may matter to your business.
| Review area | How we can help |
|---|---|
| Primary focus | Understanding business priorities and potential losses |
| Risk analysis | Reviewing operations and business risks |
| Contract review | Comparing contract terms with insurance |
| Claims handling | Supporting clients at claim time |
| Program design | Coordinating cover across business needs |
Tailoring Insurance for Complex Business Risks
If your business works in engineering, manufacturing or healthcare, you may have specialised insurance needs. We can help you review policy limits and exclusions, which describe limits on cover and matters the policy does not cover. Terms depend on the policy and circumstances.
Management liability protects business owners and managers against liabilities arising from how the business is run, depending on the policy. We can review it alongside property, liability and professional indemnity cover to help identify potential gaps. Consider the relevant Product Disclosure Statement (PDS) and speak with our team about your circumstances.
Working with an Experienced Commercial Broker
At BIS, we work on our clients’ behalf to review cover and policy terms, negotiate with insurers and explain policy conditions in plain English.
Our Role as Your Insurance Broker
Business Insurance Specialists provides commercial insurance broking from Brisbane. We work on your behalf and can help you understand your insurance options in practical terms.
We may assist with complex or hard-to-place commercial risks in certain cases, but not every risk is insurable. Before renewal or before signing a contract, gather your current policies and note any operational changes so we can have a more useful conversation about your arrangements.
Key Milestones for Reviewing Your Risk Management Strategy
It can be helpful to review your insurance when your business reaches milestones such as:
- Corporate transactions, including mergers, acquisitions, joint ventures or changes in business structure.
- Operational expansion, including new locations, facilities or staff.
- Asset acquisition, such as commercial property, specialised machinery or technology.
- Major contracts, public tenders or commercial leases with compensation obligations and insurance requirements.
- Regulatory or market changes that affect licence conditions or industry requirements.
If one of these changes is on the horizon, we can help you review your current arrangements before you make the next move.
A Practical Next Step for Risk Management and Insurance
A structured approach to risk management and insurance can support long-term business stability. By reviewing risks, taking practical prevention measures and considering appropriate cover, you can be better prepared for disruption. How and when a policy responds depends on its wording.
At BIS, our Brisbane-based team provides clear commercial insurance advice and claims support. If you are reviewing your current insurance program or considering new risk management strategies, you can request insurance quotes or contact our Brisbane team.
The information in this article is general in nature and does not take into account your objectives, financial situation or needs. Before making a decision about insurance, consider whether the information is appropriate for you and read the relevant Product Disclosure Statement (PDS) and Target Market Determination (TMD).
Frequently Asked Questions About Risk Management Insurance Services
What do risk management insurance services involve?
We help you understand business risks, consider practical prevention measures and review insurance alongside your operations and plans. Cover and service options depend on the policy and your circumstances, so speak with our team about your needs.
What factors influence commercial insurance premiums across Australian industries?
There is no fixed price for commercial insurance. Premiums depend on your business activities, cover, claims history, assets, location, risk profile, insurer and market conditions. We can talk through the factors that may be relevant to your circumstances.
What is the difference between public liability, professional indemnity and management liability cover?
Public liability generally covers injury or damage to third parties arising from business activities. Professional indemnity generally covers financial loss suffered by third parties due to negligent advice, an error or an omission. Management liability generally protects business owners and managers against liabilities arising from how the business is run. Cover depends on the specific policy and insurer terms.
What is the role of an insurance broker during a major claim or dispute?
We assist with lodging and managing claims through to finalisation. If an underwriter questions or disputes a claim, Business Insurance Specialists acts as your advocate—reviewing policy terms, examining risk documentation, and presenting technical counter-arguments through the insurer’s formal Internal Dispute Resolution (IDR) process.
